

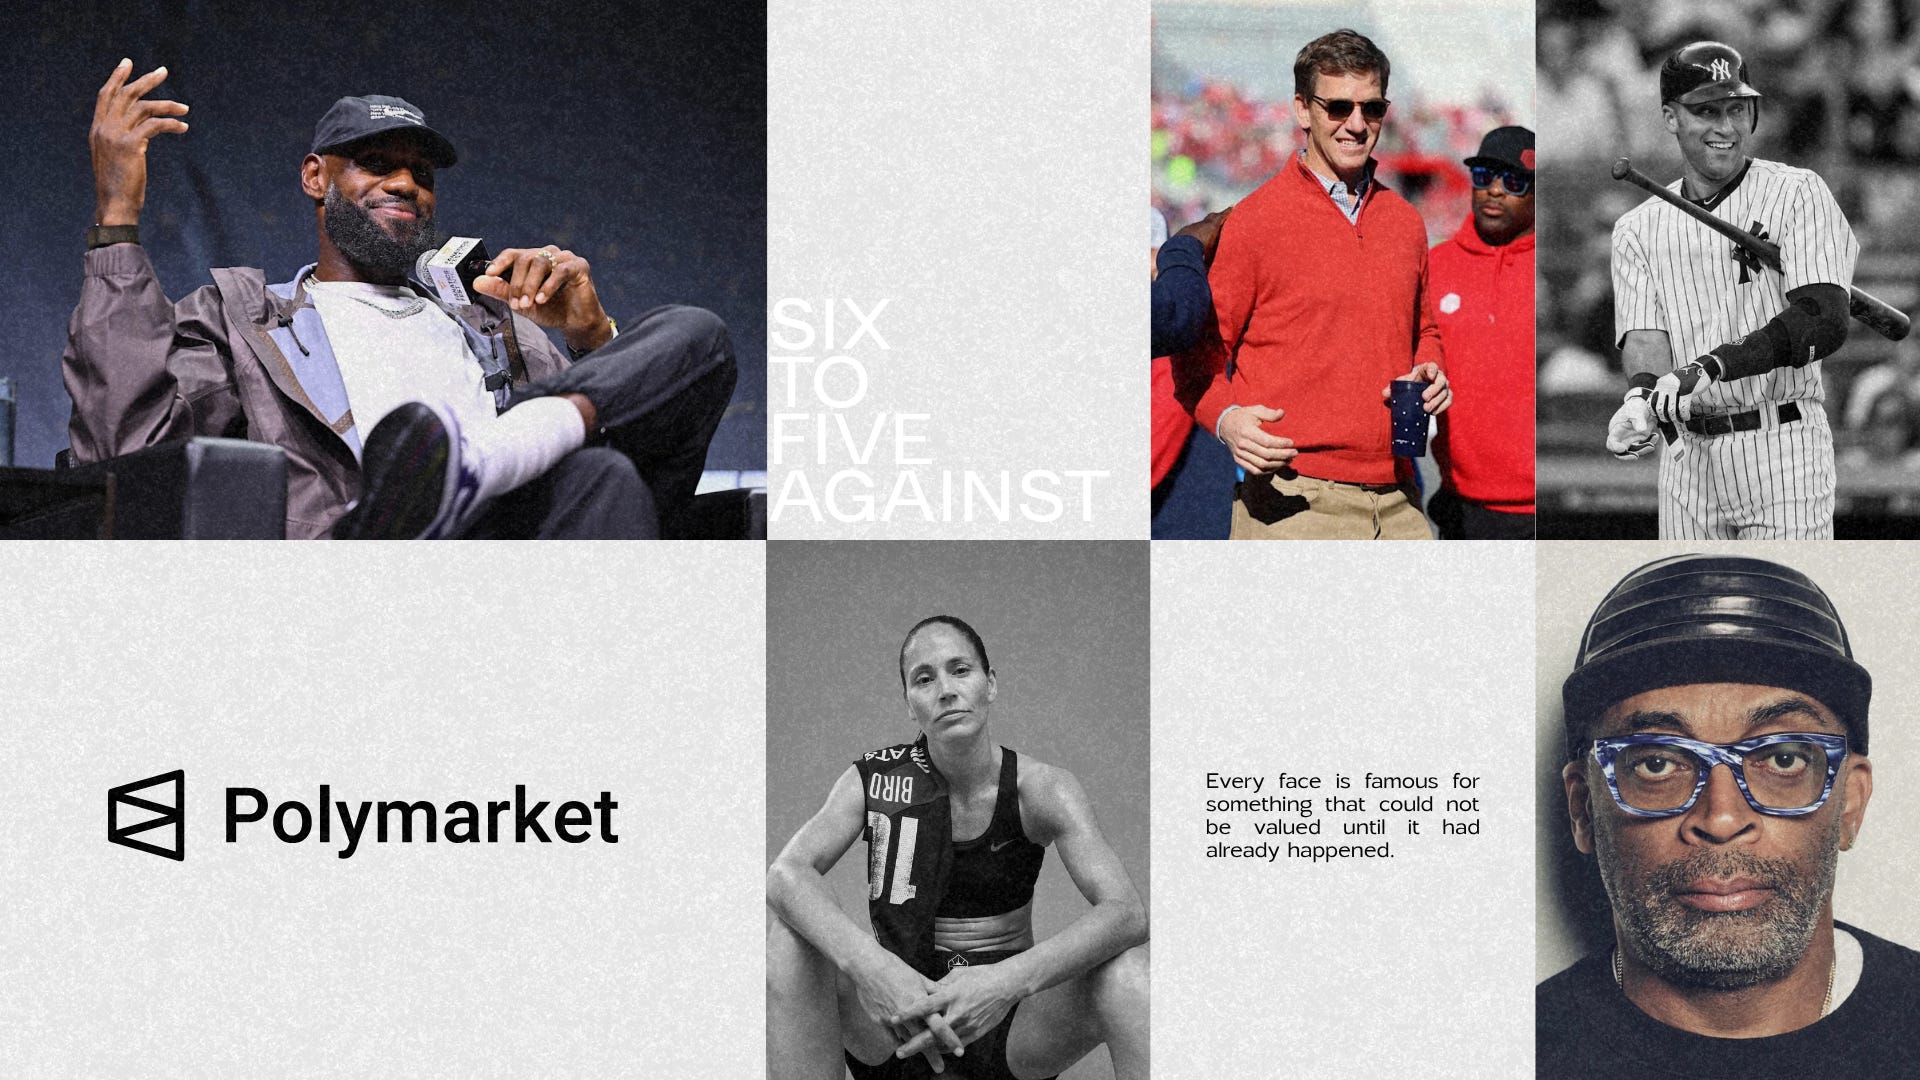
There is a fictional office tower in Polymarket’s new advertisement where every floor is a different market. It went up yesterday. LeBron James is in it. So are Derek Jeter, Sue Bird, Richard Sherman, Spike Lee, and Eli Manning — who is famous, permanently and entirely, for being the reason a number was wrong.
It was directed by Peter Berg, who made Friday Night Lights, which is the definitive American story about men who could not work out what a season had been worth until it was over.
Before anything else: the replies are full of people calling this degenerate sellout garbage, and most of them do not know what they are looking at.
Prediction markets are the most honest information instrument built this century. They update in seconds. They beat pundits and they embarrass polling more often than polling likes to admit. Above all they force people to put money behind claims that are otherwise free to make, which is the only mechanism anyone has ever found for making talk expensive. We have said so twice in this publication and we will say it again. The people mocking that advertisement are mostly mocking something more rigorous than whatever they trust instead.
So the objection is not that the tower exists. The objection is that it has a top.
In April we wrote about gasoline and insurance, and traced the same expansion in stages: markets learned to price sport, then players, then performance, then behavior, and finally the world. We said we had stopped asking what is happening and started asking what is this worth. Polymarket has now built that essay as a set. Each floor a market, the lift running upward, a famous face on every landing.
Ride it far enough and you find the thing nobody in the advertisement mentions.
A market requires a settlement event. Not as a feature — as a definition. There has to be a resolution date, an oracle that reads the result, and a payout that follows from it. Without those three things you do not have a mispriced market or a thin market or an illiquid one. You have no market at all, because there is nothing for a price to be a price of. A price is a claim about a settlement, and no settlement means no claim.
Which means the tower cannot have a floor for anything that never resolves.
Your own life is the largest unresolved position in existence. There is no date on it, no oracle, no counterparty, and — this is the part that actually matters — no way to transfer it. You cannot sell an hour of it to somebody who wants it more. Non-transferable assets have no price, not because nobody has got round to quoting them but because price is what emerges when two people can trade. Nobody can take the other side of your Tuesday.
And every professional in that building already knows what follows.
No serious bettor grades a position by whether it won. They grade it against the closing line — the number the market settled at, which did not exist at the moment of the decision and could not have. That is the whole discipline. It is why a good bet can lose and a stupid one can pay, and why anybody who judges their process by their balance is going to be broke or deluded within a year. You cannot evaluate a position until it closes, and the closing number is only ever visible afterward.
They apply this rigorously to money and never once to themselves.
Which is where a British hardcore band does more work than the whole advertisement. President, on a song called “Doom Loop”:
The tragedy of time is that we only understand its value after it’s become a memory.
That reads like sentiment. It is a technical description. Value is a settlement function. The reason you cannot price a stretch of your life while you are standing in it is the same reason there is no floor for it in the tower — nothing has resolved, no oracle has read the result, and the closing line has not printed yet.
Memory is the settlement. It is the only one you get, it arrives late by design, and it pays in a currency that does not convert.
Now the part that deserves a harder look, because it is where the tower stops being a metaphor.
The advertisement is selling a feature called Squads — private groups where you and your friends can trade together. Their own growth executive explained the thinking plainly: people are constantly debating what’s going to happen next with their friends and sharing predictions in group chats, and Squads brings the conversation and the trading together.
We have written about that room. The group chat was already an exchange, and always has been. There is a market maker, a sharp, a square, and one man who has never once acknowledged a loser. The collateral was your standing among people whose opinion you would deny caring about, and the settlement system was memory, and the exit was already expensive — changing your mind means unwinding a position in front of everyone who watched you open it.
Squads does not create that market. It monetizes it. And the pricing tells you exactly what is being sold.
Taker fees on Polymarket run from a dollar to a dollar seventy-five per hundred shares depending on category — sports and culture sit at a dollar twenty-five. Makers pay nothing. Geopolitics is free. But the mechanism underneath is a formula, and the formula is a parabola: the fee scales with the share price multiplied by one minus the share price, which means it reaches its maximum at fifty cents and falls away toward both extremes.
Read that again slowly. The house charges most at the coin flip. The closer a question is to genuinely undecided, the more it costs to hold an opinion on it. On a near-certainty you are barely charged at all, because a near-certainty is not worth arguing about and nobody wants it.
The product was never information. It is the argument — and the operator layer has priced it by exactly how alive it is.
None of which makes the tower a fraud. It is a real building doing real work, and this publication would rather read a Polymarket line than most op-ed pages. But it has a top floor, and above it there is nothing, and the people they hired to ride the lift are the proof.
Eli Manning’s entire place in history is a number being wrong. Jeter and Bird are legacy assets — worth what they are worth only now that it is finished. Spike Lee has held a courtside position for thirty years that no exchange on earth could have quoted at the time and every one of them would price generously today.
Every face on those landings is famous for something that could not be valued until it had already happened.
The market cannot fully price the feeling. In this case it cannot even open the book.
Ride it as long as you like. There is no floor for this.