

In 1923, a passenger liner called the Reliance changed her nationality.
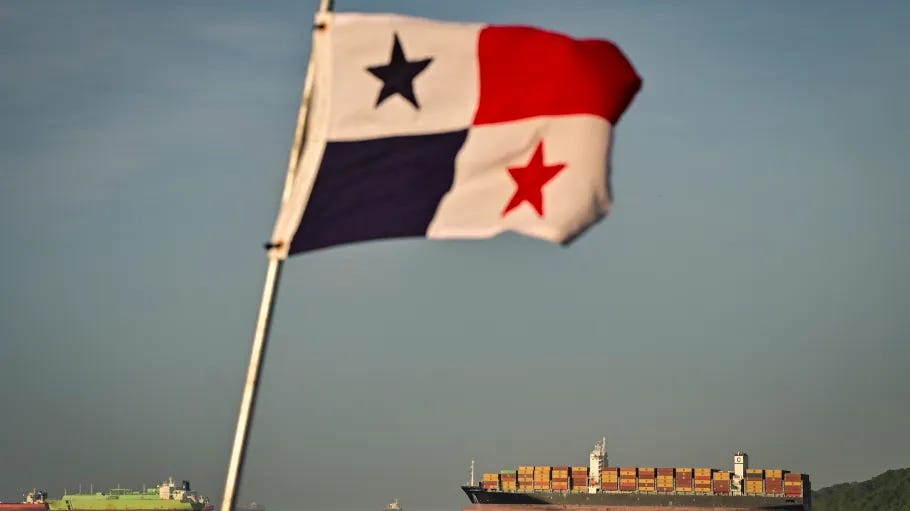
She did not change anything else. Same hull, same funnels, same crew, same Atlantic run, same owners sitting in the same offices in New York. United American Lines simply took her off the United States register and put her on Panama’s, and from that morning she was a Panamanian ship. Her sister the Resolute followed.
The reason was alcohol. Prohibition was a United States law, and it reached United States vessels. It did not reach Panamanian ones. Under the new flag the bars stayed open all the way across, and the company kept the difference.
Nobody involved pretended she was a different ship. That was never the argument. The argument was about which inspector was allowed to climb the gangway.
The idea spread the way good ideas do. A century on, Panama, Liberia and the Marshall Islands fly close to half the world’s shipping tonnage, and almost none of those ships is owned by anyone in Panama, Liberia or the Marshall Islands. The industry has a term for it. The flag of convenience. It is entirely legal, it is discussed openly at every maritime conference on earth, and it works exactly as advertised: the vessel stays where it is, and the law goes somewhere else.
Hold that picture, because it is the only one you need.
Take a Kansas City Chiefs moneyline at a sportsbook and the same contract on Kalshi, and put them side by side.
The sportsbook quotes minus 110. Convert it and you get an implied probability of 52.38 percent. That number contains the vig, so strip it out, de-vig the two-way market, and what remains is the book’s actual estimate of the outcome. Standard arithmetic, done by every serious bettor before breakfast.
The exchange quotes 62 cents. That is 62 percent, and 62 percent converts back to minus 163. There is no operation you can perform on one of those numbers that you cannot perform on the other. They are the same object in different clothing, the way Fahrenheit and Celsius are the same afternoon.
So the instinct is correct, and it is worth saying plainly before anybody gets clever: at the level of the price, a prediction market is a betting market. Same position, same event, same settlement, same arithmetic. The percentage is not a new instrument. It is American odds with the vig moved somewhere you have to look for it.
If the story ended there it would be a story about marketing, and a boring one.
It does not end there, and the next part is the part nobody writing angry threads about this has bothered to learn.
A sportsbook is your counterparty. It takes the other side. When you win, it pays out of its own pocket, and it does not enjoy that, which is why it reserves the right to stop doing business with you.
This is not a rumor. In September 2024 the Massachusetts Gaming Commission sat the operators down and asked them about it in public. BetMGM said roughly one percent of its Massachusetts customers had limits imposed. FanDuel said 0.043 percent of bets hit a maximum. The operators gave reasons — syndicates, stale lines, latency on data feeds — and the reasons are real enough. Then they conceded the part that matters: they generally do not tell you. Telling people generates complaints. So the customer finds out on his own, on a Sunday, when the maximum bet on a game quietly becomes eight dollars and stays there forever.
An exchange cannot do that. Not because it is more virtuous, but because it is not on the other side of your trade. Kalshi does not care which team wins. It matches you against another customer and clips a fee from the transaction. Being right, on an order book, is not a problem to be managed. It is just a bid.
The cost is lower too, and the gap is not small. Kalshi’s fee is 0.07 × C × P × (1 − P), which tops out at a coin flip and falls away toward the extremes — we have written about that parabola before, and it remains the most honest thing on the platform, because it charges you most for the questions that are genuinely undecided. Across 2025 the exchange did 23.8 billion dollars of volume and took 263.5 million in fees. Call it 1.1 percent.
In the same year, American sportsbooks took 166.94 billion dollars in handle and kept 16.96 billion. That is a hold of 10.1 percent. Straight sides are cheaper than that — realized hold on non-parlay betting ran under two percent recently, because sharp money grinds it down. The parlay line is where the money actually is, and there the hold ran 15.4 percent last month and has historically touched 24.
Those two figures are not measured the same way, and anyone who puts them next to each other without saying so is misleading you. Exchange volume is counted at face value, the full dollar a contract pays if it settles, not the money you put up. Kalshi’s own August figures show 11.4 billion actually staked against a much larger notional, and its parlay product inflates by a factor of sixteen on that basis alone.
Adjust for all of it and the conclusion survives. On straight two-way sports markets, the exchange is meaningfully cheaper than the book, you can sell your position before settlement at a real price rather than accepting the book’s cash-out number, and nobody can throttle you for winning.
That is not a con. That is a better deal, and it should be said in one sentence without hedging: on the things it does, the exchange does them better.
Which raises the question of why it needed a new name at all.
The intellectual case is older than the companies and better than either of them.
It runs through Hayek, who argued that a price is the only mechanism humans have ever built for aggregating what is scattered across thousands of heads and cannot be assembled any other way. It runs through Robin Hanson, who spent the nineties arguing that if you want to know what will happen, you should stop asking experts and start charging them. It runs through the Iowa Electronic Markets, which got a regulatory exemption in 1993 on explicitly academic terms — a few hundred dollars per trader, maximum.
And the record is real. Berg, Nelson and Rietz ran 964 polls across five presidential elections and found the Iowa market closer to the eventual outcome 74 percent of the time, with a mean absolute error of 1.82 points against the pollsters’ 3.37. Further out from election day the gap widened rather than closing.
It is also oversold. Christopher Wlezien has found that election markets, going back to the 1930s, performed no better than polls. Down-ballot accuracy in 2024 was poor, because thin markets are bad markets, and a market with four traders in it is a rumor with a decimal point. None of that demolishes the idea. It just means the idea is a tool and not a revelation.
But the government understood exactly what the tool was, once, with total clarity, in a single morning.
On July 28, 2003, two senators stood at a podium and destroyed a Pentagon research project called the Policy Analysis Market. Ron Wyden called it a federal betting parlor on atrocities and terrorism, ridiculous and grotesque. Byron Dorgan called it useless, offensive and unbelievably stupid. The Defense Department killed it within the day. John Poindexter resigned on August 13.
The detail worth keeping is that the screenshots which caused the outrage — assassinations, missile strikes — made up less than two percent of the interface and were illustrative placeholders. The thing itself was designed to price political and economic developments. It was executed for what it looked like rather than what it was, which is the only time in this entire story that anybody made that mistake in that direction.
Seven years later the scar went into the statute. When Congress wrote Dodd-Frank it added a special rule instructing the regulator that it may find an event contract contrary to the public interest if that contract involves any of four things.
Terrorism. Assassination. War. Gaming.
Three of those words are in the United States Code because of one press conference in 2003. The fourth is the word a 22 billion dollar company now lives inside.
So: what did the new flag actually buy?
Not the order book. Not the fee schedule. Not the ability to sell early. Those are engineering, and they would work under any name. What the reclassification bought is a specific list, and none of it has anything to do with better markets.
It bought three years. Kalshi’s minimum age is 18. Sports betting is 21 in most of the country. Between January and the end of August this year, users aged 18 to 21 traded 5.4 billion dollars on Kalshi, 3.9 billion of it on sports — a cohort legally barred from every regulated sportsbook in America. The company’s response is that they represent 3.14 percent of volume, and that Kalshi “does not set odds, does not act as a counterparty, and does not profit from customer losses.” All three of those statements are true. None of them is about age. Les Bernal of Stop Predatory Gambling put the other view less carefully and more usefully: they build a video game and push it at young people, and the science on what it does is not in dispute.
It bought a different tax code. If these contracts qualify under Section 1256, gains are split 60/40 — sixty percent at long-term capital rates capped at twenty, forty percent as ordinary income — and losses can be carried back three years. Gambling winnings are ordinary income, withheld at 24 percent above five thousand dollars, with losses deductible only against winnings, and only to ninety percent of them since last year’s tax act. Same wager. Two codes. The Internal Revenue Service has issued no guidance on which one applies, so the answer for now is whichever one your platform’s lawyers wrote down.
It bought the state out of the room. Commercial gaming paid 18.09 billion dollars in state gaming taxes last year. Federally regulated exchanges pay none of it. They also sit on no state self-exclusion list, fund no state problem-gambling program, and answer to no state regulator — which means the machinery a person uses to bar himself from sportsbooks does not reach them.
And it bought the map. This is the tell, and it is not an inference.
FanDuel launched its prediction market in December, in partnership with CME Group, in five states: Alabama, Alaska, South Carolina, North Dakota and South Dakota. Every one of them has refused to legalize online sports betting. And the sports contracts are written to cease in any state that legalizes it.
Read that twice. The product withdraws from markets that permit sports betting and operates only in markets that prohibit it. That is not a company seeking customers. That is a company seeking jurisdiction. The Reliance never docked in Panama either.
None of which has been settled, and the people who will settle it disagree with each other completely.
As of the morning this publishes, two federal appeals courts have examined the same contract and reached opposite conclusions. In April the Third Circuit held, two to one, that a sports event contract is a swap and therefore the states may not touch it. Judge Roth dissented in one line worth the whole opinion: if it looks like gambling, talks like gambling, and calls itself gambling, it’s gambling. On August 28 the Ninth Circuit went the other way, unanimously, and rejected the Third Circuit’s reasoning by name — placing sports bets, even when called by another name, is still gambling.
In between, a federal judge in Nevada granted Kalshi an injunction, thought about it for seven months, and dissolved his own order, writing that the products are sports wagers and everyone who sees them knows it.
Since then the federal regulator has begun suing states — Arizona, Connecticut, Illinois, Wisconsin and others — to defend its jurisdiction. Forty-four state attorneys general have written to tell that regulator it has no authority to write the rule it is drafting, in a sentence that is hard to argue with: states have long regulated gambling, including sports bets, and the federal government has not. Three petitions now sit at the Supreme Court, filed on September 2, September 9 and September 11. None has been granted. Nobody has won anything.
Here is what nags, and it is not the lawsuits.
The instrument was built to find the truth. That was the pitch in 1993 and in 2003 and it is the pitch today, and the pitch is honest, and the evidence for it is decent. Put money behind a claim and the claim gets expensive to make carelessly. That is the only mechanism anyone has ever discovered for making talk cost something.
It got built. It works. It is licensed, capitalized at 22 billion dollars, backed by the company that owns the New York Stock Exchange, and available on a phone to anyone over eighteen.
And in August, measured by money actually staked, sports was 61 percent of it. Macroeconomics and politics — the entire category the thing was invented for, the elections and the interest rates and the wars — came to six tenths of one percent. Sixty-four million dollars. In January that figure was 95.8 million, which means that while the exchange tripled in size, the part that was supposed to justify the whole exercise got smaller.
The information machine is finished and running at scale. The information is a rounding error.
So the answer to the question is yes and no, and the no is the interesting half. You are not being sold a worse product under a friendlier name; on several measures you are being sold a better one. But the friendlier name was never aimed at you. You were not the audience for it. The audience was a federal judge, and the word “swap” was not chosen because it describes the transaction more accurately than “bet.” It was chosen because of where it is filed.
Same ship. Same crew. Same cargo. New flag on the stern.
The bars stay open all the way across.